CAREERS
Financial planner shares essential money steps to take after losing your job
MyDigiFolio Editors
2 min read
CAREERS
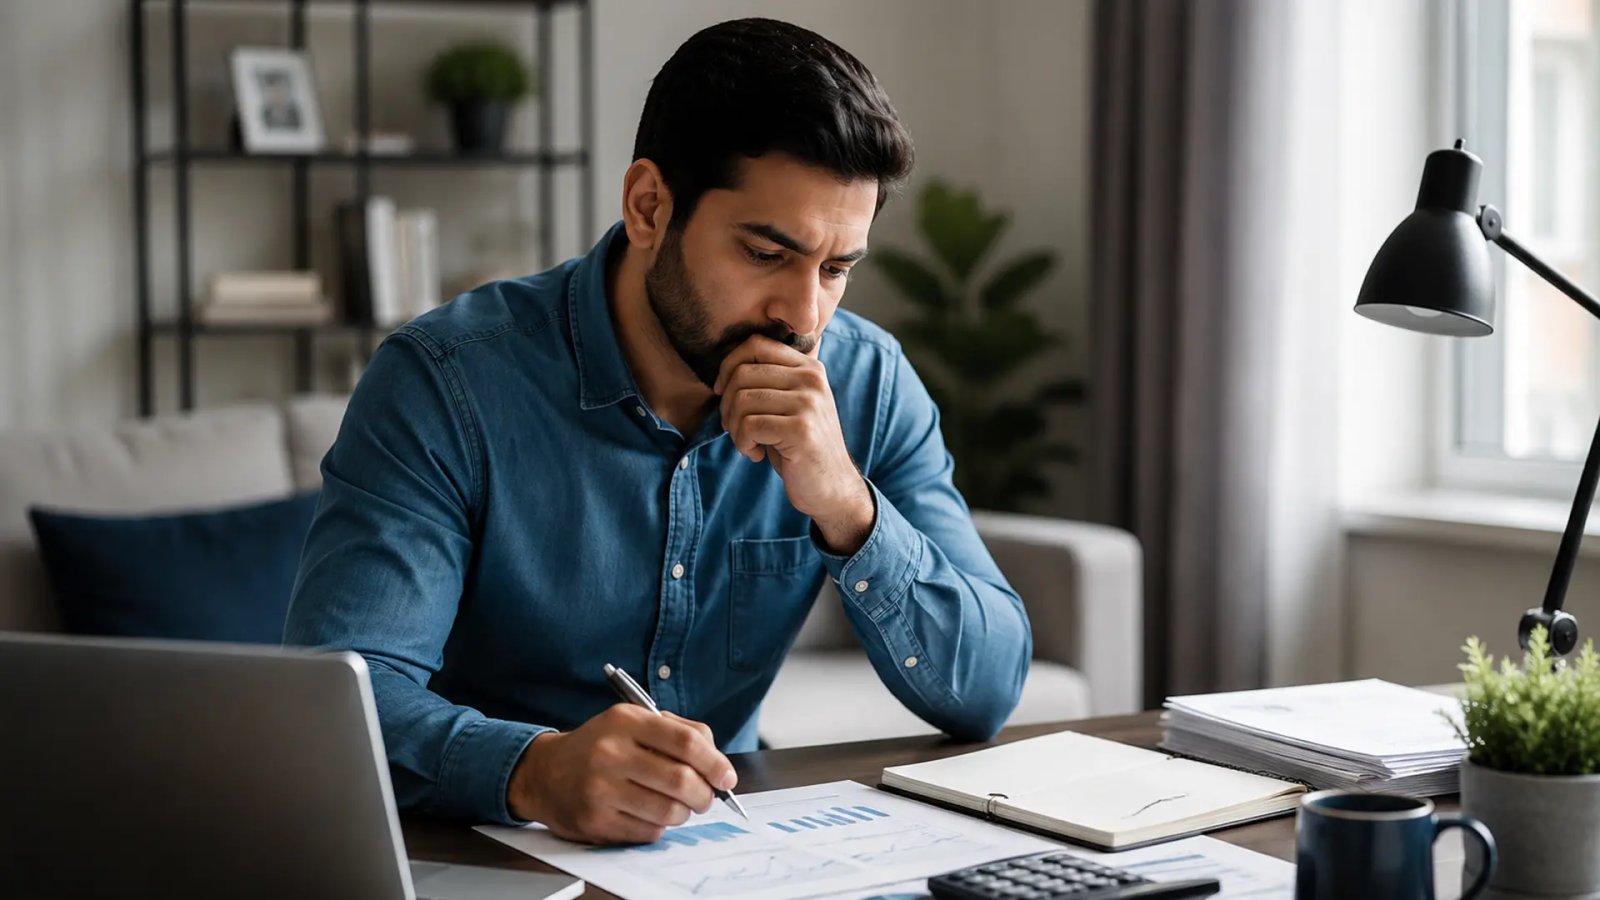
Losing a job can be stressful, but careful financial planning can help reduce uncertainty. Understanding your cash flow, protecting long-term savings and making informed decisions can provide greater stability while searching for your next opportunity.
Financial priorities after a layoff
Job cuts across the technology and corporate sectors have shown that career stability can change unexpectedly, even for experienced professionals. Certified financial planner Amber FitzRysler says the first step after a layoff is to understand your financial position and avoid making rushed decisions.
Drawing from her own experience of being laid off early in her career, FitzRysler advises people to apply for unemployment benefits as soon as they become eligible because payments may not begin immediately. She also recommends reviewing any severance package and calculating how long available savings can cover essential expenses.
Focus on cash flow, not panic
According to FitzRysler, creating a clear budget is one of the most important tasks after losing a job. She suggests separating spending into essentials, discretionary expenses and savings to identify where costs can be reduced while maintaining important needs such as food, healthcare and mental well-being.
She cautions against withdrawing money from retirement accounts early, noting that such withdrawals may trigger taxes and penalties. Instead, emergency savings should be used for their intended purpose during periods without income.
Build and rebuild an emergency fund
FitzRysler says there is no single emergency fund target that suits everyone. The appropriate amount depends on monthly expenses, job market conditions and the stability of a person's profession. Workers in industries with slower hiring cycles may need larger financial reserves than those in high-demand fields.
For people who have not yet built an emergency fund, she recommends starting with small, automated monthly contributions. After securing new employment, rebuilding the fund should become a financial priority.
Healthcare and retirement remain important
Health insurance should not be overlooked after a layoff. FitzRysler recommends comparing available coverage options and selecting a plan that balances cost with protection against unexpected medical expenses.
She also notes that many people delay restarting retirement contributions after finding a new job. Resuming long-term investing, rather than leaving savings idle, can help restore financial progress over time.
Key takeaway
FitzRysler's advice is to understand your available resources, make informed financial decisions and remember that a layoff is a temporary setback rather than a permanent situation.
ETHRWorld (The Economic Times) · 2 days ago
India’s financial crime compliance workforce is projected to expand to 45,000 by 2030, generating over 19,000 specialised jobs as global fin...
ETHRWorld (The Economic Times) · 2 days ago
As enterprises like Microsoft, Barclays, and Kroger slash headcounts citing artificial intelligence, an epilogue is taking shape: the "AI bo...
The Economic Times · 6 days ago
Palantir CEO Alex Karp is bypassing standard tech career advice like learning to code or prompt models, arguing that the only two secure car...
From MyDigiFolio
One profile. Resume, vCard, portfolio, and email signatures — all generated in 3 minutes.
Build your page — freeWe use essential cookies for login and preferences, and optional cookies for analytics. Privacy policy.